
Guaranteed and Projected Property Returns: What Investors Need to Know
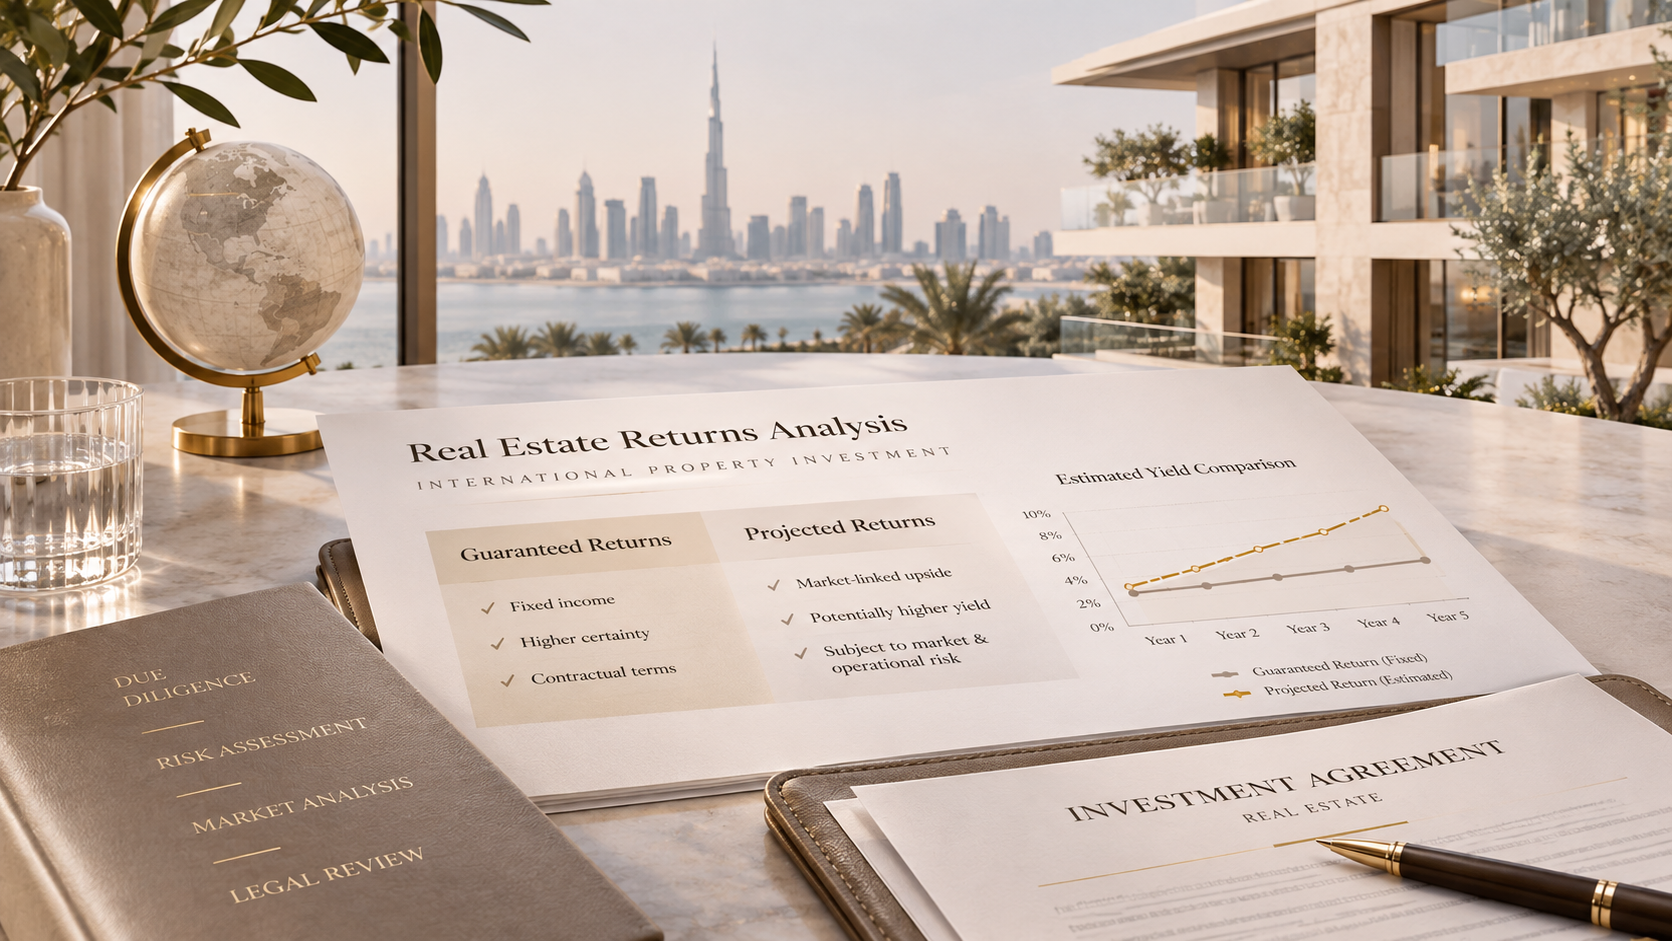
The international property market offers a wide range of investment models. Some focus on generating rental income, while others are designed around the potential for capital appreciation. A separate category includes developments in which developers or management companies offer fixed payments over a specified period.
Marketing materials for such properties frequently refer to “guaranteed returns” and “projected returns”. Although these terms may appear similar, there is a fundamental distinction between them from both a legal and an economic perspective.
For investors, it is essential to understand not only the advertised percentage but also how income is generated, where payments come from and the risks associated with a failure to meet contractual obligations.
What Are Projected Returns?
Projected returns represent an expected financial outcome calculated on the basis of assumptions about a property’s future performance.
For residential property, projections may take into account average rental rates, anticipated occupancy, maintenance costs and applicable taxes.
For hotel property, the financial model is generally more complex. It may incorporate room occupancy rates, the average daily room rate, revenue from additional services, operating expenses and management fees.
However, a financial projection does not automatically create a contractual obligation to pay the investor the stated amount.
Actual returns may be higher or lower than initially forecast.
Performance can be influenced by market conditions, competition, seasonality, management efficiency, changes in tax legislation and other factors.
A robust financial forecast should therefore include not only a base-case scenario but also an assessment of potential variations in performance.
What Do Guaranteed Returns Mean?
In the property sector, the term “guaranteed returns” is often used to describe a contractual arrangement under which a company undertakes to make fixed payments to an investor.
For example, an agreement may provide for the payment of a specified percentage of the property’s purchase price over several years.
However, it is important to distinguish between two different concepts: a contractual obligation to make payments and an effective guarantee that the investor will actually receive those funds.
Even where payments are expressly stipulated in an agreement, their fulfilment depends on the financial capacity of the party responsible.
If that company experiences liquidity problems, insolvency or other financial difficulties, the investor may not receive the agreed payments on time or in full.
A contractual commitment to a fixed return does not, therefore, eliminate investment risk.
Who Is Responsible for Making the Payments?
One of the most important considerations when evaluating a fixed-return property investment is identifying the party legally responsible for meeting the financial obligations.
This may be the developer, the owner of the operating business, a tenant, a management company or a special-purpose entity established for the project.
The involvement of a well-known hotel brand does not necessarily mean that the international hotel group itself guarantees the investor’s income.
In many developments, the brand operates under a franchise or management agreement, while financial obligations to property owners rest with a separate legal entity.
It is therefore essential to establish who the contracting party is, what assets that company holds and whether any additional security supports its obligations.
How Should Investors Assess the Financial Model?
Before evaluating the attractiveness of an advertised return, investors should establish how that return has been calculated.
For example, if a property costs €200,000 and generates annual income of €16,000, the nominal annual return is 8%.
However, this figure alone does not provide a complete picture of the investment’s financial performance.
Investors should determine whether the calculation includes acquisition costs, taxes, management fees, insurance, repairs, furnishing and other expenses.
It is also important to establish whether the advertised return is gross or net.
Gross yield expresses income as a proportion of the property’s value without fully accounting for associated expenses.
Net yield takes specified operating expenses into account and provides a more accurate indication of the financial performance of property ownership.
Nevertheless, even net operating yield may differ from the actual return on the investor’s total committed capital once transaction costs, financing and investor-level taxes are considered.
Which Risks Deserve Particular Attention?
Several categories of risk should be considered when assessing a property investment opportunity.
Counterparty risk. The company responsible for making payments may become financially unable to fulfil its obligations.
Operational risk. The property’s actual operating performance may fall below expectations.
Market risk. Changes in demand, competition or economic conditions may affect both rental returns and the property’s market value.
Legal risk. Contractual terms may provide insufficient protection for the purchaser or make the enforcement of obligations more difficult.
Liquidity risk. Even a property generating regular payments may be difficult to sell at the desired price.
Particular attention should also be paid to arrangements in which fixed payments are funded from sources other than the property’s operating profits.
Such a structure is not necessarily unacceptable, but investors should understand its underlying economic sustainability.
Should Investors Choose Properties Offering Fixed Payments?
There is no universal answer.
For a purchaser seeking predictable cash flow, a contractual fixed-payment arrangement may be an attractive option.
However, its suitability depends on the financial strength of the counterparty, contractual terms, acquisition price and the investor’s ability to sell the asset in the future.
Other investors may prefer a model in which returns are directly linked to the property’s actual operating performance.
The key is to compare not only the advertised percentages but also the risks underlying each investment structure.
Conclusion
Returns are an important consideration when evaluating investment property, but they should never be the sole criterion.
A professional assessment should examine the property’s financial fundamentals, the legal structure of the transaction, the financial position of the responsible parties, potential liquidity and possible future scenarios.
At Trustmont Capital, we approach international property through the lens of each client’s objectives, whether these involve generating passive income, seeking potential capital appreciation or diversifying assets.
Considering an investment in overseas property? Contact Trustmont Capital to discuss your strategy and the criteria for evaluating international property opportunities.